All Categories
Featured
Top-Rated IUL Benefits for Secure Retirement Planning

Top Medicare Supplement Coverage Comparison Tips
Indexed Universal Life Benefits for Retirement
Table of Contents
As quickly as the very first premium is paid, the entire death benefit is set aside for your family. Income tax-free survivor benefit: The death benefit of a life insurance policy is not usually based on federal income taxes. Tax-deferred growth: The growth of cash worth within entire life insurance is tax-deferred while the funds remain in the policy.
This indicates withdrawals to the extent of expense basis are thought about an income tax-free return of expense basis. Tax-favorable access to cash worth loans for any factor: Throughout the insured's life, cash worth loans taken against an entire life policy are not thought about to be a taxable event, although the policy may have a big gain in excess of premiums paid.
Term vs Whole Life InsuranceSelf-funding: The policy can pay for itself with time by using dividends to pay premiums, which adds to the policy's savings component. Impairment defense: An entire life policy can continue to be funded even if you are handicapped. When you choose the Waiver of Premium rider9, if you suffer a certifying impairment, your policy will continue to supply survivor benefit security, have cash worth growth, and pay dividends even while you aren't paying premiums.

10Distribution: If effectively executed, life insurance helps avoid probate and can provide recipients with greater personal privacy than may be paid for by a will; a will becomes public when probated, whereas survivor benefit circulations are typically private, contractually driven transactions. When a policy loan has actually been taken, the yearly dividend can be utilized to help pay back the policy loan.
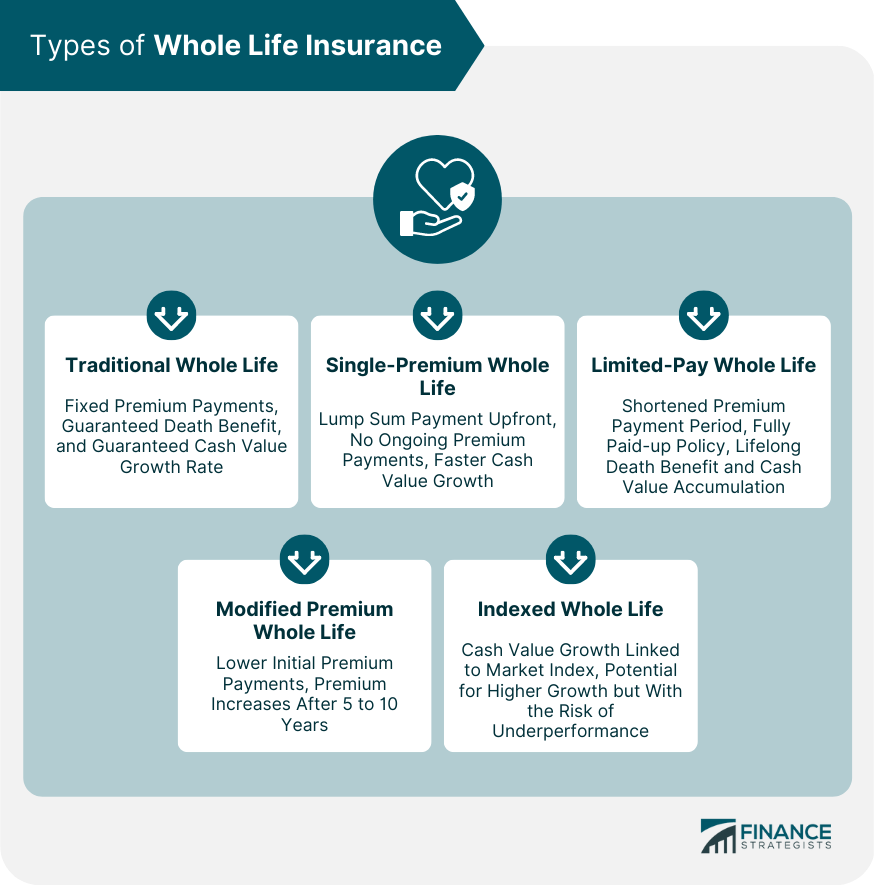
Functions, provisions, and expenses vary from one insurance provider to the next, and each entire life agreement is distinct to the policyholder. Whole life insurance rates depend upon factors such as age, health, and protection quantity, so it is essential to think about these when examining policies. Generally speaking, there are two basic kinds of payment structures for entire life: Level premium entire life: This is the most typical type of whole life insurance.
Term vs Whole Life InsuranceMedicare Part D Coverage and Drug Advice
Minimal payment whole life: This kind of policy has a set level premium like a level premium entire life policy, however the premium is just payable for a fixed period of time. The benefit is that they are ensured to be paid up at the end of the payment duration, so no payment is needed at later ages.
Their accessibility and expense depends upon the policy and the insurer. In addition to the Waiver of Premium rider pointed out above, some other choices offered by Guardian include: Paid-Up Additions Rider: The PUA rider can assist increase the build-up of tax-deferred money worths and death benefit. The higher the premium paid into the rider, the greater the defense afforded by the policy.
It offers you an unique chance for index-linked upside potential and the flooring guarantees that your year-to-year drawback market direct exposure is limited. Accidental Death Benefit: Offers an additional survivor benefit if death takes place by accidental physical injury. Accelerated Benefit Rider: Provides accelerated benefits, permitting you to access a part of the death advantage early if you are diagnosed with a persistent or terminal disease.
Choosing PPO vs PPO Health Insurance Coverage
Guaranteed Insurability Choice (GIO): Provides the policy owner the right to buy additional insurance coverage without proof of insurability. The GIO can end up being even more valuable in the occasion of special needs: A guaranteed who is disabled and has their premium waived may exercise the GIO rider, and Guardian will pay the premium on the new policy An entire life insurance coverage policy is among the most essential monetary purchases you can make.
12 Comparing life insurance companies and their life insurance offerings such as whole life, universal life, repaired premiums, guaranteed death advantages, and cash value development is necessary to discovering the ideal policy for your needs. There are reputable, independent sources for financial strength rankings, such as A.M. Finest, Moody's, Requirement & Poor's and Fitch.
Discuss your situation with an insurance expert or financial professional who comprehends entire life insurance coverage and can assist you to the service that best satisfies your needs. If you don't understand such a professional, ask a good friend or coworker for a suggestion.
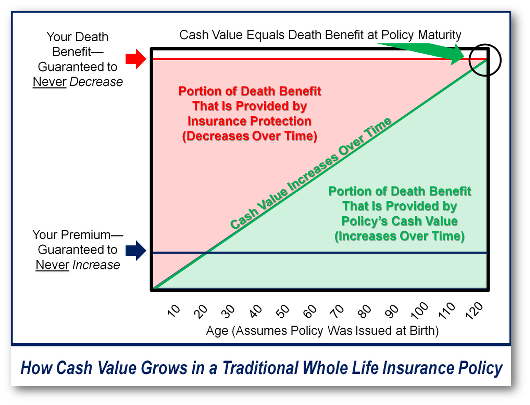
An entire life policy has money value that grows in time. You can cash it out to assist supplement retirement, or obtain versus it at any time, for any reason. Whole life policies have a component referred to as the policy's cash value: A portion of your premium dollars can grow gradually on a tax-deferred basis, so you don't pay taxes on the gains.

Latest Posts
Top-Rated IUL Benefits for Secure Retirement Planning

Why Whole Life Builds Value

Financial Security Strategies Through Term Life Insurance