All Categories
Featured

Best Indexed Universal Life Strategies for Retirement
Nationwide likewise gives you the capability to essentially buy additional upside possible with their "High-Cap" or "High-Par" Indexed Universal Life insurance coverage investment strategies, which feature an additional 1%-2% fee. Although this reduces an IUL's floor below 0%, there may be years when you desire the extra upside potential. Diverse Set of IUL Crediting StrategiesUnique Multi-Index StrategyHistory of Treating Inforce Policyholders FairlyLarge Size, Mutuality, and Solid Financial StrengthStrong concentrate on Volatility Control IndexesGood long-lasting growth, however dull early cash valuesParticipating policy loan rate is capped to be no greater than 8% Columbus Life Insurance is the IUL arm of the well-rated insurance corporation of Western Southern Group, which got in the IUL arms race in the middle of the last years.
Because their only responsibility as a business is to the long-term obligation of policyholders, they are most likely to do right by their inforce block of organization. This can be clearly seen in this screenshot we just recently sent to one of our clients demonstrating how Columbus Life's IUL cap rates have actually steadily increased from 8.75% in December 2022 to 10% precisely one year later as rates ticked up.

The worst IUL business continually declare to have the finest Indexed Universal Life insurance policy with the highest cap. However, they'll start with a very high cap to capture market share, then quickly pull the carpet out from under their customers once they shelve that product and begin a brand-new one.
That way, insurance policy holders borrowing for outside investment opportunities still had the potential to earn a minimum of some favorable arbitrage. Strong S&P 500 cap rateParticipating loan rate is topped at 6% (but has been lower for a while)Their recorded history of treating in-force insurance policy holders fairlyMutual Holding Business with no outdoors stockholdersTheir uncapped indexed account is currently unappealing and inactionable.
To clarify, all the best IUL business in this article provide some sort of complimentary chronic health problem rider, however National Life Group's is perhaps the most robust. I likewise wish to mention that I am specifically discussing their "Peak Life" product, which is their "larger case" item using a more streamlined charge structure.
Building Family Wealth with Whole Life Insurance
Technically the rider is "totally free", however we've discovered when stress-testing fees that the death costs are a bit greater than other of the very best IUL business. This is to be expected, and you may have heard me state, "There's rarely any handle insurance. Everything gets priced perfectly rather rapidly."That stated, National Life Group remains in the running for the best Indexed Universal Life insurance company for clients searching for a balance of efficiency, earnings, and comprehensive security.
Insurance in Seal Beach CADon't invest too much time on these information as your numbers will certainly differ, however this reveals the type of chronic disease rider payments they offer. to discover out which are presently the best IUL policies with robust Chronic Disease Riders and solid IUL crediting strategies for tax-free earnings if you do not become too sick or hurt to work independently.
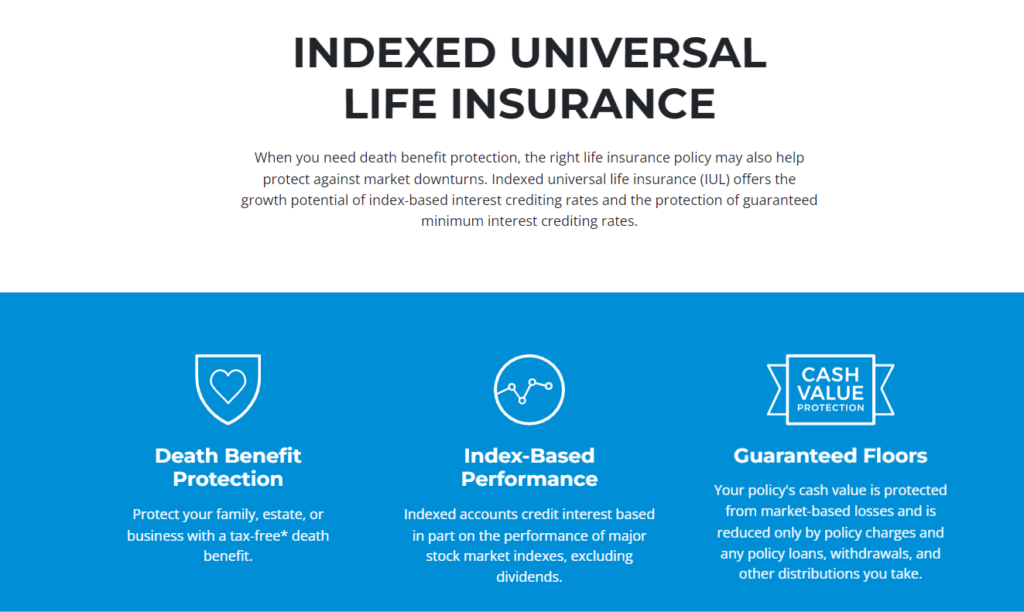
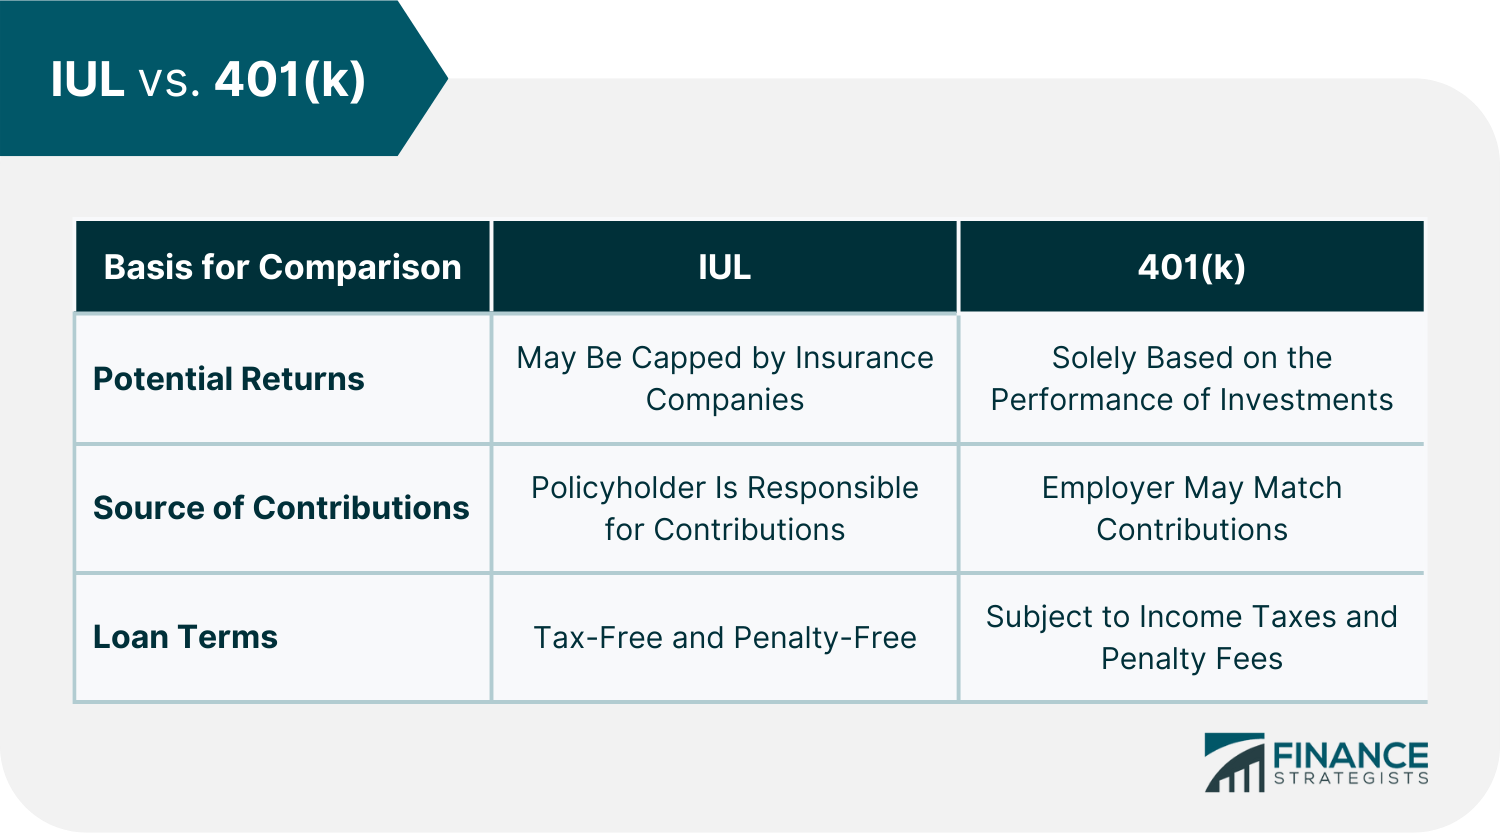
Indexed Universal Life Insurance has so numerous moving parts at its core, not to discuss all the potential bells and whistles different business include to their policies. If you're weighing IUL versus your existing retirement accounts, our complete breakdown of covers the key differences in contribution limitations, tax treatment, and versatility.
Throughout many of the 1900s the only life insurance coverage products were Whole Life and Term. Term insurance provided lower costs for temporary life insurance protection. Whole Life supplied a guaranteed survivor benefit for a guaranteed level premium, but likewise had actually a connected cost savings element with an ensured permanent growth rate along with non-guaranteed dividends.
Top Medigap Plans
The idea with Universal Life is that the development of the cost savings account will lower the amount of pure insurance coverage in the policy, which would lower the rising expense per system of survivor benefit. In 1986, soon after the meteoric rise of Universal Life, life insurance companies had the idea of adding a financial investment element.
In 1997, the very first Indexed Universal Life product was created by TransAmerica (not on the list of 2026 Best IUL companies). At initially, Indexed Universal Life insurance coverage didn't make a huge splash at all.

Latest Posts

Term Insurance Options for Seniors in 2026
Affordable Burial Insurance Coverage
Evaluating IUL Policies During Retirement